

Top Software Companies in Melbourne (423)
Founded in Chicago in 1987 by Stan Day, SRAM, LLC has grown to be one of the world's largest bicycle component manufacturers. Today, we are led by CEO, Ken Lousberg, and Stan Day serves as Chairman of our Board. SRAM’s global footprint helps us bring cycling to every corner of the globe, including your local roads and trails. We design and...

SRAM, LLC's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Evidence indicates revenue returned to growth in 2025 and remained above pre-pandemic levels, aided by aftermarket demand and normalized inventories. This signals a recovery trajectory supported by ongoing investments rather than a transient spike.
Market Expansion: A planned 270,000-square-foot factory in Portugal with phased operations from 2028 and 500+ projected jobs, plus a new Italian facility combining Ochain operations with technical service, extend the European footprint. These moves increase regional capacity and proximity to dealers and OEMs.
Product Line Growth: New releases such as RED AXS and Force AXS, alongside acquisitions including Ochain and earlier additions like Hammerhead and TIME, broaden the component and technology portfolio. This expanded lineup supports engagement across premium segments and the aftermarket.
CSC is a global leader in providing business, legal, tax, and digital brand services to companies around the world. With more than 8,000 employees, CSC operates in more than 140 jurisdictions, delivering solutions that help businesses thrive. We pride ourselves on our client-focused approach, market-leading expertise, and unmatched global reach.
CSC's Top Stability & Growth Strengths
Market Expansion: Capabilities in more than 140 jurisdictions, the completed Intertrust integration, and investment in a larger Luxembourg office indicate sustained geographic scale-up. Acquisitions such as Intertrust and Eddystone broadened presence across Europe and Asia-Pacific while deepening local delivery.
Strong Market Position & Advantage: Adoption by a large majority of major enterprises and top global brands, plus category strength in registered agent and enterprise domain management, point to entrenched competitive standing. Independent industry recognition in capital-markets operations further underscores visibility in core niches.
Investor Backing & Capital Strength: Independent credit analyses reference mid‑single‑digit organic growth expectations, high profitability, and a large recurring-revenue base, supporting stable financing capacity. Deleveraging and an upgrade from a major ratings agency suggest solid access to capital and prudent balance‑sheet management.
A leading global aerospace company and top U.S. exporter, Boeing develops, manufactures and services commercial airplanes, defense products and space systems for customers in more than 150 countries. Our U.S. and global workforce and supplier base drive innovation, economic opportunity, sustainability and community impact. Boeing is committed to fostering a culture based on our core values of safety, quality and...

Boeing's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year in early 2026, supported by higher commercial-aircraft deliveries and a record company backlog. Results indicate top-line momentum as production and deliveries recover toward pre-2019 levels.
Diversified Revenue Streams: Defense and services activity are contributing alongside Commercial Airplanes, with defense volumes growing and services providing recurring support. This breadth helps buffer the business while commercial programs ramp.
Strong Market Position & Advantage: A record multi-year backlog and status as one of two dominant large-jet manufacturers point to durable demand and competitive strength. Ongoing order activity and planned production rate increases reinforce this position.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating profitability is strengthening, with Q2 2026 delivering a 27% adjusted operating margin and 65% growth in adjusted diluted EPS. For 2025, operating income also rose to $1.7B, highlighting improved earnings leverage.
Resilient & Sustainable Growth: Gross profit increased every year from 2021 to 2025 and accelerated 25% year over year in Q2 2026. Management raised its 2026 gross-profit outlook to $12.51B (about 21% growth), reinforcing a multi-period expansion trend.
Cost & Operational Efficiency: Efficiency measures and AI-driven execution are associated with faster product delivery and improved profitability. Workforce streamlining and operating leverage supported margin expansion alongside growth in both Cash App and Square.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 8% in 2025 and accelerated to 14% year over year in Q2 2026, with management raising full‑year revenue guidance to $16.05–$16.22 billion. Gross bookings also rose 8% in 2025 and 12% in Q2 2026, indicating expanding underlying travel activity.
Profitability: Operating income grew 42% in 2025 and surged 65% in Q2 2026, while GAAP net income jumped 166% in that quarter. Adjusted EBITDA rose 19% in 2025 and 23% in Q2 2026, suggesting improved operating leverage alongside growth.
Diversified Revenue Streams: Both distribution channels are contributing, with Q2 2026 B2B gross bookings up 21% (B2B revenue up 23%) and B2C gross bookings up 8%. Lodging remained a key driver as lodging gross bookings rose 11% and booked room nights increased 6% in Q2 2026.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising at a strong, double‑digit pace across recent quarters and years, with subscription sales increasing alongside total revenue. Company guidance for subscription revenue was raised, reinforcing the momentum.
Resilient & Sustainable Growth: Remaining performance obligations and current contracted revenue expanded, indicating meaningful visibility into future sales. Growth in large enterprise customers and multi‑million‑dollar deals further supports durability.
Innovation-Driven Growth: AI offerings became a meaningful commercial driver as ServiceNow AI exceeded $1 billion in annual contract value and deployments accelerated. Adoption of workflow and AI products is highlighted as a primary catalyst.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Gross profit is rising strongly year over year, indicating expanding earnings power in the Cash App segment. This momentum is paired with gains across card spending, banking, and lending.
Diversified Revenue Streams: Expansion beyond peer-to-peer into banking, investing, lending, card, buy-now-pay-later, and commerce provides multiple monetization levers. Growth in primary banking activity and lending originations suggests broader product contribution to results.
Cost & Operational Efficiency: Operating discipline and AI-enabled processes are enabling more output with a smaller workforce. Financial performance improving alongside restructuring points to efficiency gains rather than scale-driven headcount growth.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and annual recurring revenue each rose 25% in fiscal 2026, with fourth-quarter revenue also up 25% year over year. Management still expects continued double-digit growth in fiscal 2027, albeit at a slower pace.
Healthy Cash Flow: Operating cash flow reached about $1.13 billion and free cash flow was roughly $779.1 million in fiscal 2026. This points to robust cash generation alongside expansion.
Product Line Growth: The platform is expanding into AI security, data security, SASE, and agentic security operations. Security-for-AI bookings were reported to increase more than 50% sequentially in the fourth quarter, indicating early traction.
Riskified (NYSE:RSKD) empowers businesses to unleash ecommerce growth by outsmarting risk. Many of the world’s biggest brands and publicly traded companies selling online rely on Riskified for guaranteed protection against chargebacks, to fight fraud and policy abuse at scale, and to improve customer retention. Developed and managed by the largest team of ecommerce risk analysts, data scientists and researchers, Riskified’s...

Riskified's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating, with Q2 2026 rising 22% year over year to $98.7 million and first-half 2026 up about 14%, while management raised full-year revenue guidance to $400–$410 million. This momentum follows relatively modest 2025 growth, indicating a notable reacceleration in 2026.
Healthy Cash Flow: Cash generation improved, with Q2 2026 free cash flow of $12.9 million versus $5.3 million a year earlier and stronger operating leverage reflected in higher adjusted EBITDA. This suggests the business is converting growth into better cash performance even as GAAP profitability remains mixed.
Market Expansion: Business activity is broadening, with Q2 2026 GMV up 13% year over year to $41.3 billion, new merchant wins across all four regions, and expansion into additional payment types like ACH. Rising GMV alongside revenue indicates growth supported by increased platform usage, not just pricing.

We started a movement in which everyone can win – shoppers, retailers, society and every person on our team. To play fair, trust people and reward them for doing the right thing. We see and feel the impact of our work as more and more people gain financial freedom and retailers grow across the globe. Founded seven years ago in Sydney,...
Afterpay's Top Stability & Growth Strengths
Strong Revenue Growth: Afterpay-related revenue increased in Block’s latest reporting, with Afterpay Post-Purchase contributing higher year-over-year dollars in Q2 and the first half of 2026. Filings indicate the BNPL product is scaling within the parent company’s results.
Strong Market Position & Advantage: Independent estimates place Afterpay/Block in a leading position in U.S. BNPL issuance and Pay-in-4 lending. This standing suggests competitive advantage as the service expands into more everyday spending categories.
Customer Loyalty & Retention: Company materials describe the vast majority of gross merchandise value coming from returning customers. This repeat usage points to durable engagement across its merchant network.
HERE Technologies is a location data and technology company that created the first digital map over 35 years ago. Today we are the world's leading location platform company with a global footprint across 52 countries. Although our strongest presence is in the automotive industry, we also work with leading companies across a wide range of industries, including transport and logistics,...
HERE Technologies's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent industry rankings place the company at the top of location-platform evaluations for nine consecutive years, reinforcing sustained competitive strength. Scale indicators note its platform in 238 million vehicles by 2026 and leadership recognition across most evaluation categories.
Market Expansion: Automotive reach broadened to 238 million vehicles worldwide by 2026, with more than 63 million using its data for ADAS and automated driving. Customer penetration includes all 10 of China’s top vehicle exporters in 2025, indicating deeper access to a key growth market.
Strategic Partnerships: A 10-year, $1 billion cloud agreement with AWS, an expanded Hyundai AutoEver online-navigation program covering 1+ million vehicles, and collaborations with Samsara and Esri highlight expanding distribution and co-innovation. These alliances support scale in automotive, logistics, and AI-enabled location services.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Operating and net income remained positive even as revenue softened in recent quarters. This indicates an earnings base that is holding up during a period of slower demand.
Healthy Cash Flow: Free cash flow stayed positive with meaningful generation quarter to quarter, and guidance points to continued cash production. Liquidity is reinforced by a sizable balance of cash, cash equivalents, and government securities.
Future-Ready Strategy: Management is concentrating investment on the Command Platform, detection and response, exposure management, and AI-enabled security operations. This refocus aims to position the portfolio for a return to growth once the transition progresses.
For more than two decades, Imprivata has been redefining how life- and mission-critical industries secure and manage digital identities. We empower healthcare and enterprise organizations to enable fast, compliant, and secure access to technology—allowing clinicians and staff to stay focused on what matters most: patient care and operational excellence. Our digital identity platform is purpose-built for complex environments where every second...

Imprivata's Top Stability & Growth Strengths
Strong Revenue Growth: Recurring revenue and contract billings have been rising at low-teen rates since 2022, with expectations for continued double-digit top-line expansion. Reporting also indicates meaningful revenue scale with rapid momentum.
Healthy Cash Flow: Financial analysis points to improving cash generation, with free cash flow expected to increase materially over the near term. This trend signals growing operating efficiency alongside revenue expansion.
Customer Loyalty & Retention: Gross retention remains very high and net revenue retention is described as strong, indicating renewals plus expansion within the existing base. These metrics point to a sticky customer franchise supportive of durable growth.

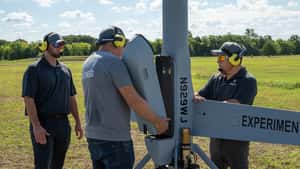
At Shield you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under a...
Shield 's Top Stability & Growth Strengths
Strong Revenue Growth: Company updates describe orders and revenue doubling year over year in FY2026, with independent estimates showing substantial growth through 2024. Additional reporting notes a projection of more than 80% revenue growth for 2026.
Investor Backing & Capital Strength: A $2 billion financing package in March 2026 at a $12.7 billion post-money valuation is cited, including a large Series G and preferred equity. The capital was linked to expansion initiatives and the planned acquisition of Aechelon Technology.
Market Expansion: New defense wins and international deployments are described, including a U.S. Air Force production contract, Coast Guard and Navy programs, and activity across Europe and the Asia-Pacific. Company communications also highlight wider adoption of Hivemind and expansion of V-BAT operations.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Strong Revenue Growth: Square’s segment revenue increased 10% in 2025 and rose 16% year over year in Q2 2026, pointing to renewed topline momentum. These gains accompany rising seller activity and broader ecosystem adoption.
Profitability: Gross profit reached about $1.16 billion in Q2 2026, up 13% year over year, after a 9% increase for full-year 2025. The trend indicates improving economic contribution from processing, software, and financial services.
Market Expansion: International GPV grew 28% year over year in Q2 2026 while U.S. GPV rose 10%, alongside traction with larger merchants and vertical solutions such as restaurants and banking. These patterns suggest widening geographic and segment reach.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Historical 2022 results showed robust year-over-year expansion, and leadership later indicated the business was heading toward about $2 billion in revenue. These signals indicate meaningful scale and ongoing momentum.
Innovation-Driven Growth: AI product adoption and platform usage have surged since 2023, with a sizable share of customers upgrading to new AI capabilities. Company disclosures describe sharp increases in monthly active AI users and total interactions analyzed on the platform.
Market Expansion: Completion of the $6.75B Press Ganey Forsta acquisition broadens reach into healthcare experience data, relationships, and analytics. This materially expands the company’s footprint and opportunities for cross-sell.
Genius Sports is the layer between what happens on the field and how the world engages with it. Our solutions across the global sports ecosystem are underpinned by our next generation big data and artificial intelligence platform, GeniusIQ. By ingesting and computing multiple real-time data feeds, GeniusIQ powers a wide range of functions and applications across sports performance and officiation, fan engagement,...

Genius Sports's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding quickly across recent years and into 2026, with broad-based gains in betting and media and an increased full-year outlook. The acceleration predates the latest acquisition, indicating underlying momentum in the core business.
Innovation-Driven Growth: Media and advertising products powered by platforms like GeniusIQ and BetVision are gaining traction, contributing to rapid expansion in the media technology segment. Betting technology is also advancing through added services, contract renewals, and new customer wins.
Future-Ready Strategy: Management raised full-year guidance and outlined multi-year targets while extending into adjacent areas such as digital sports media and prediction markets. The Legend acquisition expands capabilities and audience reach that can support the next phase of scale.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 38% year over year to $427.3M in Q2 FY2027, with subscription revenue up 37% and subscription ARR up 33% to $1.66B. Enterprise adoption is also rising, with customers generating at least $100K in subscription ARR growing from 2,505 to 3,084 year over year.
Healthy Cash Flow: Free cash flow was positive at $65.7M in Q2 FY2027, up from $57.5M a year earlier. Operating leverage is improving as subscription ARR contribution margin increased to 14.0% from 9.4%.
Investor Backing & Capital Strength: Liquidity is substantial, with $1.75B in cash, cash equivalents and short‑term investments as of July 31, 2026. This balance sheet capacity provides flexibility to fund continued growth and execution.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is advancing at double-digit rates across multiple periods, with FY2026 revenue rising 19% to about $2.02B and fiscal Q1 FY2027 revenue up 16% to $555M. ARR also increased 17% in the latest quarter, reinforcing breadth of growth in a subscription model.
Healthy Cash Flow: Cash generation is robust, including approximately $529M in free cash flow for FY2026 and operating cash flow of roughly $306M in Q1 FY2027. These indicators suggest expansion is supported by solid liquidity rather than heavy cash burn.
Product Line Growth: Log management is scaling rapidly, with annualized consumption reaching about $200M in Q1 FY2027 and growing at more than 100% year over year. Investment in AI-powered operations and platform capabilities is extending the growth runway.
InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Strong Hiring & Retention: Employee headcount is increasing over the 2023–2026 period, indicating ongoing hiring momentum. Feedback suggests workforce expansion is sustained even if the pace has moderated recently.
Market Expansion: A new Jakarta office was opened in 2026 to deepen engagement across Southeast Asia. Operations span dozens of offices in many countries, supporting customers in more than 80 countries.
Innovation-Driven Growth: New offerings such as the Data Studio AI Assistant and continued development of healthcare interoperability products point to active product investment. Feedback suggests AI and healthcare enhancements are a current strategic focus.



