Top IT Companies in Melbourne (287)
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.

At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profitability is trending upward in 2026, with management twice raising full-year adjusted EBIT guidance and North America’s EBIT margin improving to 8.6%. Strong demand, improved margins, lower EV losses, and higher operating efficiency are cited as drivers.
Strong Market Position & Advantage: Market position in the U.S. remains strong, with 2025 deliveries up 6% to about 2.9 million and market share rising to roughly 17.2%, alongside leadership in full-size pickups and full-size SUVs. Several brands posted record or decade-best results, and crossovers grew to more than 46% of sales by Q1 2026.
Healthy Cash Flow: Cash generation is viewed as robust, with executives indicating more than $10 billion of free cash flow per year on average over the last five years. Capital returns were reinforced by a higher dividend and a new $6 billion share repurchase authorization.
Xero is small business accounting software that provides a platform on which businesses can build a fully integrated solution. It’s designed to make life better for people in small business, their advisors, and communities around the world. Xero minimises tedious admin by automating routine tasks, delivers valuable insights when needed, and brings together business data, trusted advisors, and powerful apps...
Xero's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show operating revenue rising at double‑digit rates across FY2025 and FY2026, with annualized recurring revenue increasing even faster. Growth is supported by both subscriber additions and higher average revenue per customer.
Healthy Cash Flow: Free cash flow increased year over year, indicating stronger cash generation alongside expansion. Reported figures highlight rising cash metrics even as the company scales investments.
Market Expansion: International revenue and subscribers continued to grow, with substantial gains outside Australia/New Zealand and ongoing progress in the U.S. aided by product and acquisition initiatives. Regional momentum in markets like the UK and North America underscores a widening footprint.
A leading global aerospace company and top U.S. exporter, Boeing develops, manufactures and services commercial airplanes, defense products and space systems for customers in more than 150 countries. Our U.S. and global workforce and supplier base drive innovation, economic opportunity, sustainability and community impact. Boeing is committed to fostering a culture based on our core values of safety, quality and...

Boeing's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with H1 2026 up 11% and Q1/Q2 growing 14% and 8% respectively, supported by higher commercial-aircraft deliveries. This momentum reflects increased production throughput and broader top-line recovery.
Healthy Cash Flow: Cash generation is improving, as H1 2026 operating cash flow turned positive and free cash flow improved, including a positive result in Q2. This shift indicates better working-capital dynamics alongside rising delivery volume.
Strong Market Position & Advantage: Backlog is at a record level of roughly $715 billion, including more than 6,200 commercial aircraft. This depth of contracted demand provides multi‑year visibility for production and revenue.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising from $1.62B in FY2023 to $2.17B in FY2024, $2.67B in FY2025, and about $3.35B in FY2026, with Q4 FY2026 up 25% year over year. This trajectory, alongside mid‑20% ARR growth, indicates continued expansion rather than a stall.
Healthy Cash Flow: Cash generation is growing, with free cash flow rising to about $779M in FY2026 and a free‑cash‑flow margin near 23%. Non‑GAAP operating metrics, including an ~80% gross margin, underscore operating leverage.
Strong Market Position & Advantage: Industry evaluations list the company as a Leader in the 2026 Gartner Magic Quadrants for both SSE and SASE, with five consecutive years of SSE leadership. Expanding large‑enterprise adoption and thousands of customers support a durable position in its core zero trust/SSE markets.
For more than two decades, Imprivata has been redefining how life- and mission-critical industries secure and manage digital identities. We empower healthcare and enterprise organizations to enable fast, compliant, and secure access to technology—allowing clinicians and staff to stay focused on what matters most: patient care and operational excellence. Our digital identity platform is purpose-built for complex environments where every second...

Imprivata's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as sizable and growing rapidly, with independent reporting and credit analyses pointing to continued double‑digit expansion. ARR and ACV are characterized as increasing consistently since 2022.
Customer Loyalty & Retention: Retention is depicted as very high, with consistent expansion within existing accounts that supports sustained recurring revenue growth. Commentary highlights strong share‑of‑wallet gains and durable renewals across healthcare customers.
Product Line Growth: The portfolio has broadened through repeated acquisitions (e.g., SecureLink, Verosint) and new capabilities such as passwordless authentication and agentic identity management. These moves signal active investment to expand addressable use cases and deepen the platform.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Bottom-line performance is strengthening, with consistent earnings beats, improved non-GAAP operating income, and durable free cash flow. Management is prioritizing margin expansion alongside operational efficiency.
Healthy Cash Flow: The business is generating solid free cash flow, with recent periods and guidance pointing to sustained cash generation. This supports stability even as revenue growth moderates.
Strong Market Position & Advantage: The company is repeatedly recognized as a leader in MDR, exposure management, and SIEM by major analyst programs. A large global customer base underscores established scale in its core markets.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.

As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is presented as expanding substantially across fiscal 2026 and into fiscal 2027, with multiple consecutive quarters showing strong year-over-year increases. The momentum spans both total revenue and subscription metrics, indicating broad-based top-line expansion.
Healthy Cash Flow: Operating cash flow and free cash flow are described as improving markedly, moving from modest levels to solid positive generation. Recent results also point to expanding contribution margins, suggesting better unit economics as scale increases.
Customer Loyalty & Retention: Average subscription dollar-based net retention is noted as comfortably above the expansion threshold, implying existing customers are growing their spend. Growth in the cohort of customers generating at least $100K in subscription ARR reinforces durable land-and-expand dynamics.
HERE Technologies is a location data and technology company that created the first digital map over 35 years ago. Today we are the world's leading location platform company with a global footprint across 52 countries. Although our strongest presence is in the automotive industry, we also work with leading companies across a wide range of industries, including transport and logistics,...
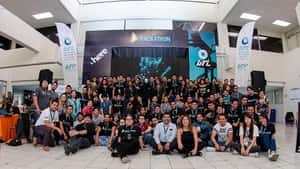
HERE Technologies's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with automakers such as Hyundai AutoEver, Lotus, and Amap, alongside cloud collaborations like AWS and ecosystem ties with Esri, continue to expand. These relationships appear to deepen distribution and integration across automotive and enterprise use cases.
Innovation-Driven Growth: The portfolio is expanding into AI, software-defined vehicles, ADAS, autonomous driving, and logistics, with launches such as HERE SDK updates and Location Reasoning. This trajectory indicates increasing focus on higher-value, future-oriented offerings.
Strong Market Position & Advantage: Independent analyst indices (Omdia and Counterpoint) repeatedly place the company at the top of location-platform rankings, and installed vehicle use rose from 222M to 238M. These signals point to sustained competitive standing and broad automotive adoption.
OneTrust, the AI-Ready Governance Platform™, enables innovation through the responsible use of data and AI. Trusted by over half of the Fortune 500, we help businesses govern well and move fast, turning responsible data use into a catalyst for growth.

OneTrust's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analyst placements repeatedly position the company as a Leader in privacy management, supporting a strong competitive standing in its core niche. A large enterprise footprint is indicated by broad adoption among major global organizations and extensive customer scale.
Strong Revenue Growth: Revenue trajectory is described as scaling rapidly, with recurring-revenue milestones referenced and an ambition to further expand annual recurring revenue. Growth is also framed as being supported by expanding demand for compliance and AI-governance capabilities.
Investor Backing & Capital Strength: Large cumulative funding and multiple major rounds are cited, indicating significant capital availability to fund expansion and product development. Valuation and financing events are presented as providing resources to continue investing through market cycles.
At Planit, we provide businesses with the vision, precision and independence they need to improve the quality of their software and the way they deliver it. As a global leader in quality engineering and assurance solutions, our 2,000+ consultants are at the forefront of the industry. Every day, they test themselves on a variety of challenging projects across our top-tier client...

Entrust offers identity-based security software and services.
Entrust's Top Stability & Growth Strengths
Future-Ready Strategy: Signals indicate Entrust is advancing a PQC-forward roadmap with FIPS 140-3 validated nShield 5 HSMs and NIST CAVP progress, aligning to regulated and government workloads. Product launches like its unified Cryptographic Security Platform position the company for crypto-agility across keys, certificates, and secrets.
Product Line Growth: Feedback suggests the Onfido acquisition materially expanded Entrust’s identity verification portfolio, with identity verification revenues surpassing $180 million in the year following the deal. Continued updates in instant issuance and PKI/HSM offerings further broaden the product mix.
Strong Market Position & Advantage: Independent coverage places Entrust as a Leader in instant card issuance and a top-tier, certification-validated HSM provider, with strong standing in enterprise PKI. These positions reinforce competitive advantage in high-assurance, compliance-driven segments.
Cevo is a technology consultancy that helps organizations build lasting capabilities in cloud, data, and AI. They focus on modernizing platforms, automating delivery, and empowering teams to innovate continuously. By embedding AI into their delivery processes, they help clients move from pilots to production-ready systems, ensuring that transformation becomes a habit rather than a one-off project.
.jpeg)
Infosys is a global leader in next-generation digital services and consulting. We enable clients in more than 50 countries to navigate their digital transformation. With over three decades of experience in managing the systems and workings of global enterprises, we expertly steer our clients through their digital journey. We do it by enabling the enterprise with an AI-powered core that...
Infosys's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent rankings and analyst assessments consistently place Infosys in the Leader cohort across multiple service lines, and it competes head‑to‑head with top global peers on large, complex transformations. This breadth and scale position it well for enterprise RFPs across cloud, workplace, modernization, and industry platforms.
Strong Brand Reputation: Brand Finance places Infosys among the top three most valuable IT services brands and highlights sustained brand‑value growth, indicating strong global stature and client recognition. This brand strength supports executive access and large‑deal pursuits across key geographies.
Healthy Cash Flow: Management commentary points to solid cash generation and free cash flow even during periods of softer demand. Shareholder returns, including buybacks, reinforce underlying financial resilience.

We are a global technology consultancy that delivers extraordinary impact by blending design, engineering and AI expertise. For 30 years, our commitment to design-led thinking, engineering excellence and innovation means we prioritize people, build teams with strong technical foundations and embed AI into every step of the process – not just as a tool but as a mindset. It’s this approach...

Thoughtworks's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with hyperscalers and advisors (e.g., multi-year AWS collaboration, 2025 AWS Partner Award, and a 2026 AI-focused venture with Teneo) broaden the company’s go-to-market in AI and data services. Industry recognitions and joint initiatives are positioned to unlock new enterprise opportunities even as recent financial visibility is limited.
Future-Ready Strategy: The company is pivoting to an AI-first model, launching AI/works and advancing 50+ generative AI projects, while Technology Radar and “AI-First Consulting Firm” recognition underscore focus on emerging tech. These moves target rising demand for AI-enabled delivery and data engineering.
Cost & Operational Efficiency: Restructuring across 2023–2024 generated substantial annualized savings (e.g., $87M by Q1 2024 and about $180M by September 30, 2024), reflecting disciplined cost control. Actions indicate a concerted effort to restore margins and resilience amid softer demand.

The world’s top restaurant brands use Crunchtime to achieve ops excellence, in every location. It’s how operators manage food and labor costs, food safety, brand standards, and the overall customer experience across every location. By enabling leaders and teams to confidently manage inventory, suppliers, staff scheduling, task and audit management, and employee learning and development, the Crunchtime Operations Management Platform...

Crunchtime's Top Stability & Growth Strengths
Strong Revenue Growth: Crunchtime has surpassed $100 million in annual recurring revenue and expanded its brand and location footprint globally, indicating sustained topline momentum.
Strong Market Position & Advantage: The platform is widely adopted by leading multi‑unit restaurant brands across a large global footprint, including many of the largest U.S. chains and marquee enterprise customers.
Product Line Growth: Acquisitions such as Zenput and DiscoverLink and a merger with QSR Automations have broadened the suite across inventory, labor, ops execution, kitchen, and host, deepening cross‑product adoption.

We create intelligent systems that understand context, anticipate needs, and turn ideas into action, unlocking entirely new ways for people to work and create. The future isn’t just about software that stores information. It’s about technology that thinks, adapts, and acts. We are pioneering the next generation of AI-powered, action-driven systems that amplify human capability, accelerate workflows, and make work feel...