

Top AI Companies in Melbourne (111)
At monday.com, we help teams get more work done. We are the best AI work platform that empowers teams to automate, build, and scale their impact end-to-end with tools that actually execute the work for you. With over $1B in ARR, 250,000+ customers, and a global team, we’re serious about building a product people love to use and giving our...

monday.com's Top Stability & Growth Strengths
Profitability: Net income reached $118.7 million in 2025 versus $32.4 million in 2024 and a small loss in 2023, alongside record non‑GAAP operating income and margin improvements in 2026. This indicates the company is scaling efficiency while expanding.
Strong Revenue Growth: Revenue rose 27% in 2025 to $1.232 billion and continued to increase 22% year over year in Q2 2026, with management guiding 19%–20% growth for 2026. While the pace has moderated from earlier years, the top line remains firmly upward.
Innovation-Driven Growth: ARR from AI products doubled quarter over quarter in Q2 2026 and represented 17% of net new ARR. The pivot to an AI work platform is contributing discernible incremental demand.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Bottom-line performance is strengthening, with consistent earnings beats, improved non-GAAP operating income, and durable free cash flow. Management is prioritizing margin expansion alongside operational efficiency.
Healthy Cash Flow: The business is generating solid free cash flow, with recent periods and guidance pointing to sustained cash generation. This supports stability even as revenue growth moderates.
Strong Market Position & Advantage: The company is repeatedly recognized as a leader in MDR, exposure management, and SIEM by major analyst programs. A large global customer base underscores established scale in its core markets.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
Airwallex is the only unified payments and financial platform for global businesses. Powered by our unique combination of proprietary infrastructure and software, we empower over 250,000+ businesses worldwide – including Brex, Navan, Qantas, SHEIN, McLaren and many more – with fully integrated solutions to manage everything from business accounts, payments, spend management and treasury, to embedded finance at a global...
Airwallex's Top Stability & Growth Strengths
Strong Revenue Growth: Annualized revenue increased from $720M in March 2025 to $1.3B by March 2026, with ARR surpassing $1B in late 2025 and continuing upward. This trajectory points to sustained top-line momentum across the period cited.
Market Expansion: Geographic reach broadened with new regulated entries across multiple regions, alongside plans to deploy over $1B in the U.S. and substantial investment in Europe. Regional performance in the Americas and EMEA also advanced meaningfully, indicating traction beyond APAC.
Investor Backing & Capital Strength: Valuation rose from $6.2B (May 2025) to $11B (June 2026) through successive large funding rounds. Independent reporting corroborated the latest financing, signaling strong capital access and external confidence.
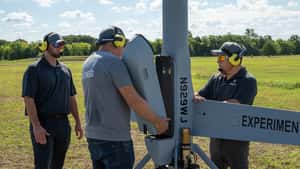
At Shield AI, you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under...
Shield AI's Top Stability & Growth Strengths
Strong Revenue Growth: Company reports indicate FY2026 orders and revenue doubled year over year. Management projections point to revenue well above $500 million for 2026, signaling rapid topline acceleration.
Investor Backing & Capital Strength: Recent financings include a $1.5 billion Series G and $500 million in preferred equity at a $12.7 billion valuation. These steps indicate substantial capital access and confidence from major financial backers.
Market Expansion: Program momentum includes a U.S. Air Force production award for CCA autonomy and a U.S. Navy ISR vehicle with a high task‑order ceiling. International traction spans India, Greece, Poland, and Taiwan, alongside plans for regional offices.
Genius Sports is the layer between what happens on the field and how the world engages with it. Our solutions across the global sports ecosystem are underpinned by our next generation big data and artificial intelligence platform, GeniusIQ. By ingesting and computing multiple real-time data feeds, GeniusIQ powers a wide range of functions and applications across sports performance and officiation, fan engagement,...
Genius Sports's Top Stability & Growth Strengths
Strong Revenue Growth: Reported results show consistent top-line increases through 2025 and into 2026, including a sharp acceleration in Q2 2026. Guidance was raised above $1B for 2026, underscoring momentum.
Strategic Partnerships: Long-term, often exclusive relationships with tier‑one rights holders such as the NFL (through 2029), Football DataCo/Premier League (through 2029) and the NCAA (through 2032) reinforce commercial visibility. These agreements expand distribution and underpin growth across betting and media.
Innovation-Driven Growth: Product advances like GeniusIQ, BetVision, and Second Spectrum tracking are cited as drivers of expanding media and betting solutions. This innovation push aligns with rapid Media segment growth and broader market expansion.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Profitability: The company is described as privately held, profitable, and debt-free, indicating a solid financial base. This positioning supports continued investment without reliance on external financing.
Strong Revenue Growth: Revenue is reported above $1 billion with indications of year-over-year increases into 2024 and sustained scale into FY2025, while cloud segments are noted as expanding strongly. These signals point to ongoing top-line momentum.
Market Expansion: Operations span 28 countries with 38 offices serving customers in 80+ countries, alongside recent moves such as a dedicated public-sector subsidiary and added international presence. This footprint suggests continued geographic and channel growth.

HERE Technologies is a location data and technology company that created the first digital map over 35 years ago. Today we are the world's leading location platform company with a global footprint across 52 countries. Although our strongest presence is in the automotive industry, we also work with leading companies across a wide range of industries, including transport and logistics,...
HERE Technologies's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with automakers such as Hyundai AutoEver, Lotus, and Amap, alongside cloud collaborations like AWS and ecosystem ties with Esri, continue to expand. These relationships appear to deepen distribution and integration across automotive and enterprise use cases.
Innovation-Driven Growth: The portfolio is expanding into AI, software-defined vehicles, ADAS, autonomous driving, and logistics, with launches such as HERE SDK updates and Location Reasoning. This trajectory indicates increasing focus on higher-value, future-oriented offerings.
Strong Market Position & Advantage: Independent analyst indices (Omdia and Counterpoint) repeatedly place the company at the top of location-platform rankings, and installed vehicle use rose from 222M to 238M. These signals point to sustained competitive standing and broad automotive adoption.
About Coursera: Coursera was launched in 2012 by Andrew Ng and Daphne Koller with a mission to provide universal access to world-class learning. Coursera partners with leading university and industry partners to offer a broad catalog of content and credentials, including courses, Specializations, Professional Certificates, and degrees. Coursera’s platform innovations — including AI-powered personalized guide and features, like Role Play and...
Coursera + Udemy 's Top Stability & Growth Strengths
Strong Market Position & Advantage: Scale of 290M+ learners and 12k–18k enterprise customers following the May 2026 combination signals a top-tier position in online learning. The combined platform also cites 95,000 creators and more than $1.5B of 2025 revenue, reinforcing competitive heft.
Strong Revenue Growth: Coursera delivered 9% revenue growth in 2025 and, after the Udemy combination, reported Q2 2026 revenue rose about 60% year over year. Management also raised full‑year 2026 reported revenue guidance to $1.220–$1.245 billion.
Diversified Revenue Streams: Multiple engines—consumer, enterprise, and subscriptions—are contributing, with Coursera’s consumer (+10%) and enterprise (+7%) segments growing in 2025. Udemy’s subscriptions (+8%) and Udemy Business revenue (+6%) expanded even as its consumer marketplace declined.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is presented as expanding substantially across fiscal 2026 and into fiscal 2027, with multiple consecutive quarters showing strong year-over-year increases. The momentum spans both total revenue and subscription metrics, indicating broad-based top-line expansion.
Healthy Cash Flow: Operating cash flow and free cash flow are described as improving markedly, moving from modest levels to solid positive generation. Recent results also point to expanding contribution margins, suggesting better unit economics as scale increases.
Customer Loyalty & Retention: Average subscription dollar-based net retention is noted as comfortably above the expansion threshold, implying existing customers are growing their spend. Growth in the cohort of customers generating at least $100K in subscription ARR reinforces durable land-and-expand dynamics.

BlueRock delivers the first Compute Firewall, revolutionizing runtime security in an era of AI-speed cyberattacks and escalating third-party software risks. Traditional security tools and agents can't keep pace, leaving enforcement gaps exposed. Attackers now exploit vulnerabilities within minutes of disclosure, outpacing reactive detection methods. BlueRock solves this by embedding real-time, preemptive enforcement directly into the compute layer, halting exploits precisely...

Canva is a free, online tool where you can create social media posts, presentations, posters, videos, logos and more. Our community of 220 million+ monthly active users is already creating 400+ designs every second, but we’re just 1% of the way to our goal. It’s hard to explain what makes life at Canva so special, but we've identified two key...
Canva's Top Stability & Growth Strengths
Strong Revenue Growth: Independent analyses and business press describe rising annualized revenue from 2024 into 2025, indicating sustained double‑digit momentum. This trajectory is repeatedly cited alongside multi‑year profitability signals.
Strong Market Position & Advantage: Sources characterize Canva as a category leader in web‑first visual communication with very large user reach and broad Fortune 500 penetration. Private‑market valuation step‑ups and widespread adoption across education, SMBs, and enterprises reinforce this position.
Product Line Growth: The company has expanded beyond its core editor via the Affinity acquisition and launches like a “Creative Operating System,” deeper AI features, and new tools such as Sheets and Code. These additions extend coverage from easy graphics into professional workflows and enterprise offerings.

The Bosch Group is a leading global supplier of technology and services. It employs roughly 402,600 associates worldwide (as of December 31, 2021). The company generated sales of 78.7 billion euros in 2021. Its operations are divided into four business sectors: Mobility Solutions, Industrial Technology, Consumer Goods, and Energy and Building Technology. As a leading IoT provider, Bosch offers innovative solutions...
Bosch Group's Top Stability & Growth Strengths
Strong Market Position & Advantage: Bosch is described as the world’s largest automotive supplier and a leader in MEMS sensors, European home appliances (via BSH), and e‑bike systems, underscoring durable competitive scale. Power tools and building technologies show top‑tier brand presence even where share leadership is contested by region and channel.
Market Expansion: In North America, 2024 consolidated sales increased to about $17.4B, signaling regional outperformance amid a soft global backdrop. Preliminary 2025 updates emphasize continued focus and scale in the region.
Future-Ready Strategy: The company is executing Strategy 2030 with targeted investments and portfolio adaptation in areas such as home comfort/heat pumps and software-defined mobility. Management messaging highlights selective growth initiatives intended to support medium‑term improvement despite near‑term pressures.

Thales is a global high technology leader investing in digital and “deep tech” innovations – connectivity, big data, artificial intelligence, cybersecurity and quantum technology – to build a future we can all trust, which is vital to the development of our societies. The company provides solutions, services and products that help its customers – businesses, organisations and states – in...
Thales's Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased in 2025 versus 2024, with early 2026 also showing higher sales and management guiding to further organic growth in 2026.
Profitability: Adjusted EBIT rose and margins improved in 2025, indicating strengthening operating performance alongside growth.
Resilient & Sustainable Growth: Record order intake and an order book above €53 billion provide multi‑year visibility, and a book‑to‑bill above 1 with reaffirmed 2026 targets supports continued expansion.
Qsic is the market leader in creating AI-driven audio retail media channels for large physical store retailers in North America and Australasia. Reach your customers at the point of purchase. Sell audio advertising packages to your suppliers. Unlock the additional revenue potential of your physical store networks.
Certn isn’t a background check provider with a tech department, it’s a tech-first leader innovating every part of the background screening process. Certn is changing background screening globally by offering the easiest-to-use platform, checks in 200+ countries and territories, free 24/7 customer support, and fast and compliant results. Trusted by 10,000+ clients, Certn helps businesses manage risk, stay compliant, and...

We are a niche, AWS data and analytics partner that specialises in helping public sector customers to unlock their vast data repositories and use the insights gained to drive better service delivery and improved programme outcomes. We use our data, analytics, AI/ML and IoT powers for good i.e. we don’t take on work where it’s clear that the outputs of what...

Nagarro helps future-proof your business through a forward-thinking, fluidic, and CARING mindset. We excel at digital engineering and help our clients become human-centric, digital-first organizations, augmenting their ability to be responsive, efficient, intimate, creative, and sustainable. Today, we are 19,000 experts across 36 countries, forming a Nation of Nagarrians, ready to help our customers succeed.
Nagarro's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Colleagues are often seen as delivering steady, continued expansion, with revenue increasing year-over-year through 2024 and into 2025 despite a subdued IT services market. Growth is also framed as durable due to continued analyst expectations for further expansion and management guidance indicating continued momentum.
Diversified Customer Base: Colleagues are often seen as benefiting from low dependency on any single client, with limited concentration among the largest accounts. The presence of many sizeable client relationships (including a large cohort of €1m+ clients) supports resilience in demand fluctuations.
Profitability: Colleagues are often seen as improving operating performance, with stronger adjusted EBITDA margins and rising EBIT in later 2025 periods. Margin expansion is linked to higher utilization and operational improvements that lifted profitability even when net profit was affected by non-operational items.



