

Top AI Companies in Melbourne (112)

At monday.com, we help teams get more work done. We are the best AI work platform that empowers teams to automate, build, and scale their impact end-to-end with tools that actually execute the work for you. With over $1B in ARR, 250,000+ customers, and a global team, we’re serious about building a product people love to use and giving our...

monday.com's Top Stability & Growth Strengths
Profitability: Net income reached $118.7 million in 2025 versus $32.4 million in 2024 and a small loss in 2023, alongside record non‑GAAP operating income and margin improvements in 2026. This indicates the company is scaling efficiency while expanding.
Strong Revenue Growth: Revenue rose 27% in 2025 to $1.232 billion and continued to increase 22% year over year in Q2 2026, with management guiding 19%–20% growth for 2026. While the pace has moderated from earlier years, the top line remains firmly upward.
Innovation-Driven Growth: ARR from AI products doubled quarter over quarter in Q2 2026 and represented 17% of net new ARR. The pivot to an AI work platform is contributing discernible incremental demand.
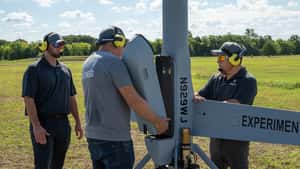
At Shield AI, you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under...
Shield AI's Top Stability & Growth Strengths
Strong Revenue Growth: Company reports indicate FY2026 orders and revenue doubled year over year. Management projections point to revenue well above $500 million for 2026, signaling rapid topline acceleration.
Investor Backing & Capital Strength: Recent financings include a $1.5 billion Series G and $500 million in preferred equity at a $12.7 billion valuation. These steps indicate substantial capital access and confidence from major financial backers.
Market Expansion: Program momentum includes a U.S. Air Force production award for CCA autonomy and a U.S. Navy ISR vehicle with a high task‑order ceiling. International traction spans India, Greece, Poland, and Taiwan, alongside plans for regional offices.
Airwallex is the only unified payments and financial platform for global businesses. Powered by our unique combination of proprietary infrastructure and software, we empower over 250,000+ businesses worldwide – including Brex, Navan, Qantas, SHEIN, McLaren and many more – with fully integrated solutions to manage everything from business accounts, payments, spend management and treasury, to embedded finance at a global...
Airwallex's Top Stability & Growth Strengths
Strong Revenue Growth: Annualized revenue increased from $720M in March 2025 to $1.3B by March 2026, with ARR surpassing $1B in late 2025 and continuing upward. This trajectory points to sustained top-line momentum across the period cited.
Market Expansion: Geographic reach broadened with new regulated entries across multiple regions, alongside plans to deploy over $1B in the U.S. and substantial investment in Europe. Regional performance in the Americas and EMEA also advanced meaningfully, indicating traction beyond APAC.
Investor Backing & Capital Strength: Valuation rose from $6.2B (May 2025) to $11B (June 2026) through successive large funding rounds. Independent reporting corroborated the latest financing, signaling strong capital access and external confidence.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Bottom-line performance is strengthening, with consistent earnings beats, improved non-GAAP operating income, and durable free cash flow. Management is prioritizing margin expansion alongside operational efficiency.
Healthy Cash Flow: The business is generating solid free cash flow, with recent periods and guidance pointing to sustained cash generation. This supports stability even as revenue growth moderates.
Strong Market Position & Advantage: The company is repeatedly recognized as a leader in MDR, exposure management, and SIEM by major analyst programs. A large global customer base underscores established scale in its core markets.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is presented as expanding substantially across fiscal 2026 and into fiscal 2027, with multiple consecutive quarters showing strong year-over-year increases. The momentum spans both total revenue and subscription metrics, indicating broad-based top-line expansion.
Healthy Cash Flow: Operating cash flow and free cash flow are described as improving markedly, moving from modest levels to solid positive generation. Recent results also point to expanding contribution margins, suggesting better unit economics as scale increases.
Customer Loyalty & Retention: Average subscription dollar-based net retention is noted as comfortably above the expansion threshold, implying existing customers are growing their spend. Growth in the cohort of customers generating at least $100K in subscription ARR reinforces durable land-and-expand dynamics.
Genius Sports is the layer between what happens on the field and how the world engages with it. Our solutions across the global sports ecosystem are underpinned by our next generation big data and artificial intelligence platform, GeniusIQ. By ingesting and computing multiple real-time data feeds, GeniusIQ powers a wide range of functions and applications across sports performance and officiation, fan engagement,...

Genius Sports's Top Stability & Growth Strengths
Strong Revenue Growth: Reported results show consistent top-line increases through 2025 and into 2026, including a sharp acceleration in Q2 2026. Guidance was raised above $1B for 2026, underscoring momentum.
Strategic Partnerships: Long-term, often exclusive relationships with tier‑one rights holders such as the NFL (through 2029), Football DataCo/Premier League (through 2029) and the NCAA (through 2032) reinforce commercial visibility. These agreements expand distribution and underpin growth across betting and media.
Innovation-Driven Growth: Product advances like GeniusIQ, BetVision, and Second Spectrum tracking are cited as drivers of expanding media and betting solutions. This innovation push aligns with rapid Media segment growth and broader market expansion.
About Coursera: Coursera was launched in 2012 by Andrew Ng and Daphne Koller with a mission to provide universal access to world-class learning. Coursera partners with leading university and industry partners to offer a broad catalog of content and credentials, including courses, Specializations, Professional Certificates, and degrees. Coursera’s platform innovations — including AI-powered personalized guide and features, like Role Play and...
Coursera + Udemy 's Top Stability & Growth Strengths
Strong Market Position & Advantage: Scale of 290M+ learners and 12k–18k enterprise customers following the May 2026 combination signals a top-tier position in online learning. The combined platform also cites 95,000 creators and more than $1.5B of 2025 revenue, reinforcing competitive heft.
Strong Revenue Growth: Coursera delivered 9% revenue growth in 2025 and, after the Udemy combination, reported Q2 2026 revenue rose about 60% year over year. Management also raised full‑year 2026 reported revenue guidance to $1.220–$1.245 billion.
Diversified Revenue Streams: Multiple engines—consumer, enterprise, and subscriptions—are contributing, with Coursera’s consumer (+10%) and enterprise (+7%) segments growing in 2025. Udemy’s subscriptions (+8%) and Udemy Business revenue (+6%) expanded even as its consumer marketplace declined.
HERE Technologies is a location data and technology company that created the first digital map over 35 years ago. Today we are the world's leading location platform company with a global footprint across 52 countries. Although our strongest presence is in the automotive industry, we also work with leading companies across a wide range of industries, including transport and logistics,...
HERE Technologies's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with automakers such as Hyundai AutoEver, Lotus, and Amap, alongside cloud collaborations like AWS and ecosystem ties with Esri, continue to expand. These relationships appear to deepen distribution and integration across automotive and enterprise use cases.
Innovation-Driven Growth: The portfolio is expanding into AI, software-defined vehicles, ADAS, autonomous driving, and logistics, with launches such as HERE SDK updates and Location Reasoning. This trajectory indicates increasing focus on higher-value, future-oriented offerings.
Strong Market Position & Advantage: Independent analyst indices (Omdia and Counterpoint) repeatedly place the company at the top of location-platform rankings, and installed vehicle use rose from 222M to 238M. These signals point to sustained competitive standing and broad automotive adoption.

Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Profitability: The company is described as privately held, profitable, and debt-free, indicating a solid financial base. This positioning supports continued investment without reliance on external financing.
Strong Revenue Growth: Revenue is reported above $1 billion with indications of year-over-year increases into 2024 and sustained scale into FY2025, while cloud segments are noted as expanding strongly. These signals point to ongoing top-line momentum.
Market Expansion: Operations span 28 countries with 38 offices serving customers in 80+ countries, alongside recent moves such as a dedicated public-sector subsidiary and added international presence. This footprint suggests continued geographic and channel growth.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
As a global leader in innovative wealth management, asset servicing and investment solutions, Northern Trust (Nasdaq: NTRS) is proud to guide the world’s most successful individuals, families and institutions by remaining true to our enduring principles of service, expertise and integrity. A globally recognized Fortune 500 Company in continuous operation since 1889, we’ve built a legacy of empowering clients to reach...

Northern Trust's Top Stability & Growth Strengths
Strong Market Position & Advantage: Scale in global asset servicing (roughly $18.6–$20.0 trillion AUC/A) and repeated leadership accolades in custody and U.S. private banking indicate a top‑tier competitive position. The franchise also competes directly with the largest providers even if it typically sits just behind the “big four” in overall custody scale.
Strong Revenue Growth: Recent results show double‑digit year‑over‑year increases in revenue and earnings, with Q2 2026 benefiting from higher fees and net interest income and management raising guidance. Multiple quarters of positive organic trust‑fee growth and expanding client assets (AUC/A and AUM up versus 2025) support momentum.
Diversified Revenue Streams: A fee‑driven mix across asset servicing/custody, wealth/private banking, and asset management underpins durability in varied market conditions. New institutional mandates, capital‑markets strength, and product/capability additions (e.g., ETFs and tokenized‑asset custody) broaden sources of growth.
Sprinklr is a provider of enterprise software for customer experience management. We help brands turn public conversations on modern channels into valuable insights to improve marketing, advertising, customer service, product development and more. Sprinklr has five products on one platform: Modern Marketing, Modern Advertising, Modern Research, Modern Care and Modern Engagement. Sprinklr’s unified platform allows siloed teams to collaborate and deliver...
Sprinklr's Top Stability & Growth Strengths
Profitability: Net margin has risen to the mid‑teens from single‑digit levels a year earlier, with Q3 FY2026 non‑GAAP operating margin in the mid‑teens and full‑year guidance targeting similar levels. Profits and EPS are expected to grow faster than revenue as margin expansion continues.
Cost & Operational Efficiency: Management is executing a transformation focused on better customer engagement, operational efficiency, and higher‑margin business rather than maximizing top‑line growth at any cost. AI‑driven products and efficiency programs are cited as key drivers of recent margin gains.
Investor Backing & Capital Strength: Cash and marketable securities of about $480M with no debt provide a strong financial position. This balance sheet flexibility supports ongoing execution through a transition year.

Pinsent Masons is a multinational law firm with a reputation for delivering high-quality legal advice rooted in its deep understanding of the sectors and geographies in which our clients operate. Our expertise is recognised globally. In recent years we have achieved more tier 1 rankings in The Legal 500 UK guide than any other firm, and been counted among the...

Snowflake powers the end-to-end data lifecycle – from ingesting and processing data to analyzing and modeling it, to building and sharing data and AI applications – helping engineers, analysts, and leaders innovate faster and achieve more with their data. We're on a mission to empower every enterprise to achieve its full potential through data and AI.

Snowflake's Top Stability & Growth Strengths
Strong Revenue Growth: Product revenue is re-accelerating, with the latest quarter marking the strongest sequential dollar increase in the company’s history and full-year guidance raised. Management also lifted the non-GAAP operating-margin outlook, reinforcing confidence in near-term growth.
Customer Loyalty & Retention: Expansion within existing accounts remains robust, with net revenue retention well above 100% and a growing cohort of large customers generating $1M+ in product revenue. Substantial remaining performance obligations add visibility to continued usage.
Strong Market Position & Advantage: The company is positioned as a Leader in Gartner’s Cloud DBMS assessment and reports deep penetration among Global 2000 enterprises. Ongoing AI and ecosystem momentum, plus multi‑cloud reach, support competitive differentiation.
Acquire Intelligence is a global business transformation company and leading provider of business process outsourcing (BPO) and AI consulting services. Using their Automate, Eliminate, Reallocate framework, they blend process improvement and automation with global outsourcing to help businesses eliminate inefficiencies, drive scale, and achieve real-world outcomes.

Affinda is your AI transformation partner. Our deep expertise in business process automation together with our proprietary intelligent document processing platform enable organizations to streamline workflows with AI, achieving real productivity gains with measurable return on investment. Around the world, leading enterprises trust Affinda to offer clear, practical AI solutions that automate their processes, boost productivity, expand margins and unlock...

Thales is a global high technology leader investing in digital and “deep tech” innovations – connectivity, big data, artificial intelligence, cybersecurity and quantum technology – to build a future we can all trust, which is vital to the development of our societies. The company provides solutions, services and products that help its customers – businesses, organisations and states – in...
Thales's Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased in 2025 versus 2024, with early 2026 also showing higher sales and management guiding to further organic growth in 2026.
Profitability: Adjusted EBIT rose and margins improved in 2025, indicating strengthening operating performance alongside growth.
Resilient & Sustainable Growth: Record order intake and an order book above €53 billion provide multi‑year visibility, and a book‑to‑bill above 1 with reaffirmed 2026 targets supports continued expansion.
.jpg)
At Cloudera, we empower people to transform complex data into clear and actionable insights. With as much data under management as the hyperscalers, we're the preferred data partner for the top companies in almost every industry. Powered by the relentless innovation of the open source community, Cloudera advances digital transformation for the world’s largest enterprises.
Cloudera's Top Stability & Growth Strengths
Strong Revenue Growth: Reported FY26 results include over 50% year-over-year growth in new and expansion business, more than 100% new-logo growth in Q4, and robust ARR momentum. Earlier periods also show year-on-year revenue and ARR increases, reinforcing the upward trajectory.
Strong Market Position & Advantage: Industry evaluations name the company a Leader in The Forrester Wave: Data Fabric Platforms (Q4 2025) and a Leader/Fast Mover in GigaOm’s 2025 Streaming Data Platforms, with additional regional leadership recognition in IDC APAC for unified AI platforms. Emphasis on hybrid/on‑prem and data sovereignty needs differentiates the platform where these requirements are paramount.
Innovation-Driven Growth: Platform scope has expanded via acquisitions (Verta, Octopai, Taikun) and releases such as Private AI Anywhere, on‑prem AI inference, and Trino-enabled warehousing. Partnerships with AWS, Intel, Dell, and VAST Data plus participation in initiatives like the AI‑RAN Alliance signal ongoing product and ecosystem advancement.



